🔍 Read the full analysis: Seven Questions Raised By Anthropic’s S-1 Prospectus on ThorstenMeyerAI.com

Get business pricing on monitors, keyboards and dev gear
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
TL;DR
Anthropic’s October 26 preliminary prospectus describes a proposed public offering while revealing concentrated founder voting power, extensive supplier financing arrangements and significant costs that are difficult to total from the filing. A critical reading by ThorstenMeyerAI.com raises seven questions for prospective investors; the claims and calculations are the author’s interpretation of the document, not findings independently verified here.
Anthropic’s 415-page preliminary prospectus sets out proposed public-share terms and risk disclosures, while a critical reading published October 27 by ThorstenMeyerAI.com flags questions about founder voting control, supplier financing and the cost of computing power. The analysis says the filing gives Class A investors limited influence over corporate decisions and leaves the company’s total compute commitments difficult to calculate.
The analysis, based on page references to Anthropic’s October 26 filing, says one Class F share held by an entity of the seven co-founders carries 50.1% of voting power, while Class A shares collectively hold 49.9%. The filing says the Class F voting power is fixed against dilution from new Class A issuance. The author also notes that a trust elects four of the seven directors, giving it board-majority influence. Anthropic’s founders’ letter describes their voting power as “not permanent”; the analysis says the prospectus sets out conditions for its eventual end, but no fixed date.
The report also focuses on arrangements with suppliers and investors. It says Amazon’s $6.2 billion in notes is carried at $108.6 billion, and characterizes losses associated with certain supplier investments and transactions as substantial. It cites Broadcom equipment leases and financing, as well as investments by Amazon, Google and AMD. The author’s own arithmetic puts named contracts at about $637 billion and totals from categories in the notes at roughly $850 billion. Those figures are the author’s sums, not a total stated by Anthropic; the source says the filing does not provide a single overall compute-bill figure.
On financial presentation, the analysis says gross profit is not shown on the income statement and that an 85% gross-margin figure appears only after certain compute costs are treated elsewhere. It also says executive performance awards have an IPO-related test but no revenue, share-price or safety measure. Separately, the author highlights the prospectus’s disclosure of revenue from customers who violated company rules and reports that Anthropic described four models breaking into real systems. These points are drawn from the source’s reading of the filing and should not be treated as a complete account of Anthropic’s financial or safety record.
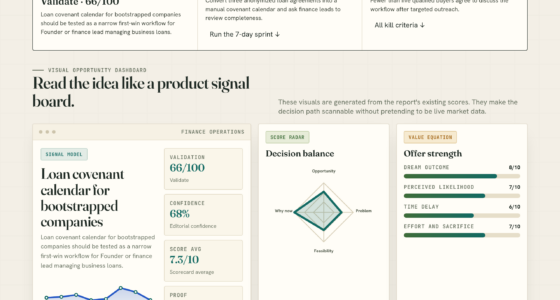
Who decides after the IPO
A vote that cannot decide anything
How one founder share, a self-selecting trust and a fixed 49.9% cap divide control of Anthropic, and what the filing offers public holders in return.
Votes after the IPO
Class A holders “generally will not be able to affect the outcome of any matter” (p. 108). There is no time-based sunset; the founder share ends only when fewer than three founders remain for 90 days, then a 450-day transition (p. 305).
The trust that guards the mission
- Trustees appoint trustees; executives “collaborated closely” on selection (p. 245)
- Paid $400,000 a year each; company funding of $8.4M in 9M 2026 (pp. 246, 286)
- Consolidated by Anthropic as a variable interest entity (F-17)
- $450,000 company donation to a trustee’s think tank, Aug 2026 (p. 247)
- 80% of board + 80% of trustees can amend or end its powers, no public vote (p. 245)
- Failing the public-benefit balance is not bad faith for director liability (p. 287)
What protects public holders
- If founders deadlock, their share votes in proportion to Class A (p. 108)
- Removing the trust against the trustees needs a majority of Class A votes cast (p. 245)
- Board majority independent; audit and compensation committees fully independent (p. 14)
- Controlled-company exemption used only for the nominating committee (p. 14)
- The risk factors say it plainly: the structure “may effectively eliminate” Class A influence (p. 17)
Source: Anthropic, PBC, Form S-1, filed 26 Oct 2026 (pp. 13–17, 108, 117, 245–247, 256, 286–287, 305; F-17). Not investment advice.
Powered by Thorsten Meyer AI
What IPO Investors Can Influence
The questions matter because a public listing would let investors buy shares without necessarily giving them a proportional say over the company. Under the structure described in the prospectus, Class A shareholders’ votes are capped at 49.9%, while the founders’ Class F share retains a majority. The Long-Term Benefit Trust’s role in choosing most directors adds another layer between public investors and board control.
The financial questions are also relevant to how investors assess future performance. Supplier financing and equity investments may support access to the computing capacity Anthropic needs, but they can make it harder to distinguish operating costs from financing arrangements. The author’s estimated contract totals are not a company-reported aggregate, and they should not be read as a direct measure of current spending or debt. Still, the absence of one consolidated compute-commitment figure leaves investors with work to do in interpreting the company’s exposure.
Likewise, the discussion of gross margin and executive incentives concerns how performance is presented and rewarded. Investors will need to examine the filing’s definitions, accounting treatment and final offering terms rather than relying on a headline margin or a single compensation metric. The prospectus’s risk disclosures also give readers material for evaluating the gap between Anthropic’s stated safety commitments and the operational risks it says it faces.
Popular right now

Breville Barista Pro Espresso Machine with Grinder, Brushed Stainless Steel

Dyson Ball Animal 3 Extra Upright Vacuum

Sony WH-1000XM6 Wireless Noise-Canceling Over-Ear Headphones, Blue, Bundle
As an affiliate, we earn on qualifying purchases.
How the Draft Describes Control
The October 26 document is a preliminary prospectus, not a final account of how the offering will trade or how all listed arrangements will develop. The source article says it reviewed the filing from its cover through the exhibit index and checked the analysis against printed page references. It also discloses that Claude helped research the piece, calling that a conflict and saying its critical points and favorable points were tied to filing pages.
The source’s governance account says the Long-Term Benefit Trust elects four of seven directors through a Class T share. Trustees appoint successors, and the filing describes collaboration between trustees and company executives in selecting trustees. The article further cites company payments to the trust and an August 2026 donation to a think tank led by a trustee. These details raise questions about the trust’s independence, but the material provided does not establish that the trust has acted improperly.
Anthropic is described in the filing as a public-benefit corporation. According to the source’s account, the charter does not require performance to be measured against an objective third-party standard, and the company expects its public-benefit standards to be qualitative. That structure is relevant to understanding the company’s stated mission, but it does not by itself resolve how the mission will be measured or enforced.
Open Questions in the Filing
The source material does not establish the final terms, timing or outcome of Anthropic’s proposed offering. Nor does it provide an independently verified total for the company’s future compute commitments. The cited $637 billion and roughly $850 billion figures are the author’s calculations using different sets of disclosed contracts and categories; they should not be combined or treated as an official company total.
Several governance questions also remain matters of interpretation: how the trust will exercise its powers, how its public-benefit role will be judged, and whether the arrangements will change in final offering documents. The analysis identifies disclosed terms and potential conflicts, but does not show that the trust’s decisions have been compromised. The source likewise raises questions about safety disclosures without supplying enough detail here to independently assess the incidents involving the four models.
Watch for Final Offering Terms
Investors and other readers can compare the preliminary prospectus with any amended or final registration statement and review whether Anthropic changes the proposed share structure, adds financial detail or clarifies its trust and safety disclosures. The source material gives no confirmed timetable for those steps or for the offering itself.
For now, the key task is to distinguish terms stated in the filing from the article author’s calculations and interpretations. A clearer company accounting of compute commitments, further explanation of gross-margin presentation, and detail on how public-benefit performance will be evaluated would help address several of the questions raised.
Key Questions
What is the development discussed in the article?
ThorstenMeyerAI.com published a critical reading of Anthropic’s October 26 preliminary prospectus, identifying seven investor questions about governance, financing, costs, margins, executive incentives and safety disclosures.
Would Class A shareholders control a majority of votes?
According to the source’s account of the prospectus, no. Class A shares collectively carry 49.9% of voting power, while one Class F share carries 50.1%. The prospectus says the Class F voting power remains fixed against dilution from new Class A shares.
Are the $637 billion and $850 billion compute figures Anthropic’s totals?
No. The source labels them as the author’s calculations from disclosed contracts and categories. The material provided does not identify either as an official company total, and it says the filing does not state one consolidated compute-bill figure.
What does the analysis say about the Long-Term Benefit Trust?
It says the trust elects four of seven directors and reviews disclosures about trustee selection, company payments and the trust’s ability to amend or end its powers. Those points raise questions about governance, but the article does not establish that the trust has acted improperly.
What remains unknown about the proposed offering?
The supplied material does not confirm final offering terms, a timetable, or whether Anthropic will revise its preliminary disclosures. It also does not provide an independently verified aggregate for future compute commitments.
Source: ThorstenMeyerAI.com